Luxury Highrises
Flood-zone and insurance ask-order for gulf-adjacent Naples towers vs inland golf — what comes first?
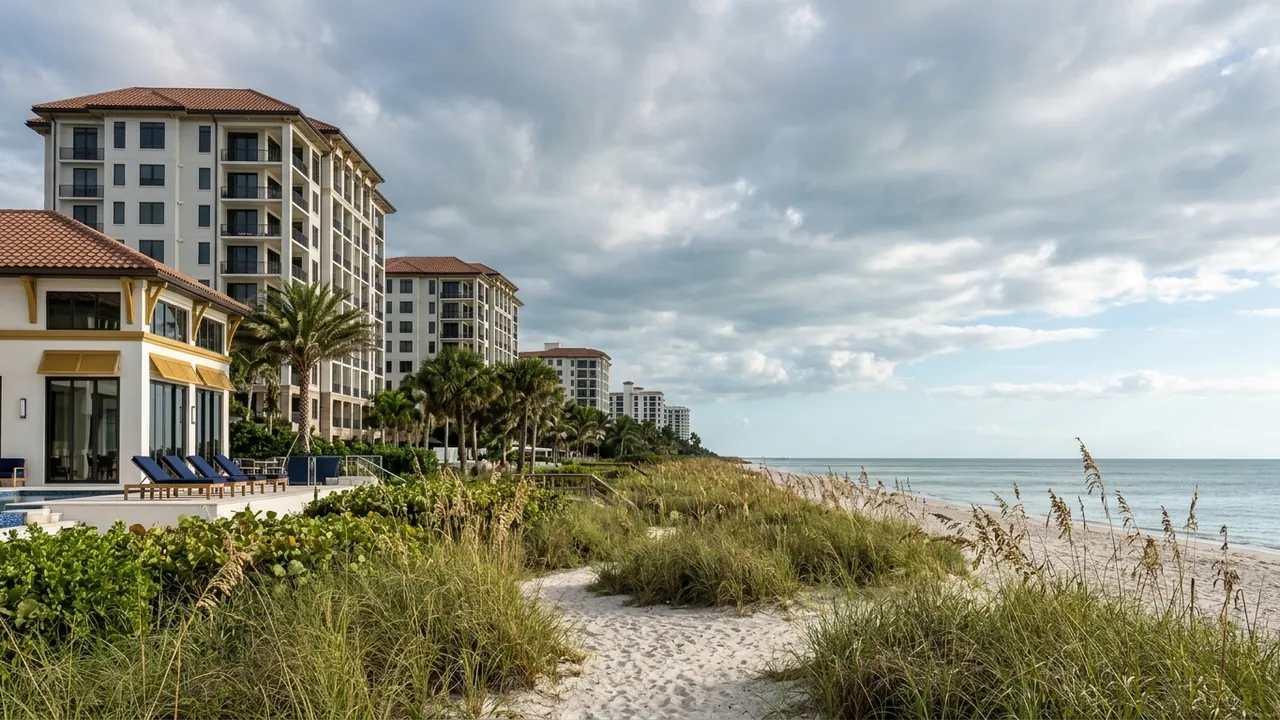
Use this order every time: (1) FEMA/City FIRM zone for the exact building or parcel, (2) association master policy and deductibles, (3) your lender’s flood requirement, (4) HO-6 / HO-3 quotes, (5) then lifestyle preference. Gulf-adjacent Naples towers and inland golf homes can sit in different FIRM panels; guessing from “near the beach” language is how buyers mis-price insurance.
On this page
- Key facts
- Ask-order (do not skip steps)
- FIRM zone labels buyers actually see
- Local example
- Comparison — gulf-adjacent tower vs inland golf parcel
- What this means for buyers
- What this means for sellers
- Quote package to send insurers (copy/paste)
- After the quote: association assessment math
- Inland golf does not mean “no flood form”
- Lender vs cash buyers—same ask-order
- One-afternoon field drill
- Why this ranks above finishes
- Document retention
- FAQ
- Sources
Key facts
- City of Naples states updated 2024 Flood Insurance Rate Maps (FIRMs) are in effect and provides AE, AH, and VE definitions for property owners. (naplesgov.com/building/page/flood-zone-maps)
- AE / AH: high-risk special flood hazard areas; federally backed mortgages typically require flood insurance. VE: coastal high-hazard with wave action. Zone X: outside the high-risk SFHA on the FIRM. (City of Naples flood materials; FEMA)
- FEMA’s Map Service Center / NFHL portal is the authoritative place to look up a panel by address (open the MSC portal; confirm the panel for the exact building). (FEMA MSC)
- Inland golf communities (e.g., Mediterra, Quail West) often sit farther from VE wave zones but can still include AE drainage/ponding panels—verify parcel by parcel. (FEMA NFHL practice)
- NABOR’s September 2026 market context does not replace a flood quote; insurance is underwritten at the structure, not at the county median. (NABOR)
Ask-order (do not skip steps)
- Pull the FIRM zone for the street address (FEMA MSC or City of Naples tools).
- Read the association’s certificate of insurance — building coverage, wind deductible, flood deductible if any, assessment provisions.
- Ask the lender whether flood insurance is required for your loan product at that zone.
- Quote HO-6 (condo) or HO-3 (home) with the same zone and year-built facts the insurer will use.
- Only then compare gulf-adjacent tower lifestyle vs inland golf lifestyle on amenity grounds.
FIRM zone labels buyers actually see
| Zone (simplified) | Meaning (City of Naples / FEMA framing) | Typical mortgage effect |
|---|---|---|
| VE | Coastal high hazard; wave action | Flood insurance usually required if federally backed loan |
| AE | High-risk SFHA; base flood elevations shown | Flood insurance usually required |
| AH | High-risk; shallow flooding / ponding characteristics | Flood insurance usually required |
| X | Outside high-risk SFHA on current FIRM | Often not required by lender; still quote for prudence |
Always confirm the panel date (City notes 2024 FIRMs in effect) so you are not reading a retired map.
Local example
Two October 2026 tours: a gulf-adjacent Naples tower and a Mediterra homesite. The tower’s FEMA lookup returns a coastal AE/VE-adjacent panel; the Mediterra parcel returns Zone X on the current panel. The buyer who obtains both flood quotes before debating Beach Club vs skyline views discovers the annual insurance delta may dwarf a small HOA difference. Reversing the order—“we love the view, we’ll sort insurance later”—is how deposits get strained.
Comparison — gulf-adjacent tower vs inland golf parcel
| Diligence item | Gulf-adjacent Naples tower | Inland golf (e.g., Mediterra / Quail West) |
|---|---|---|
| First document | FEMA/City FIRM for building | FEMA FIRM for parcel + any lake/preserve AE |
| Insurance layers | Master + HO-6 + flood | HO-3 + flood if required + club unrelated |
| Wind deductible risk | Often material; can trigger assessments | Owner-level wind deductible |
| Lifestyle trade | Walk/beach proximity | Golf / privacy / lot |
What this means for buyers
Refuse to compare buildings on HOA dues alone. Put flood and wind quotes beside the dues. If a seller cannot provide the master policy declarations quickly, treat that as a diligence delay, not a minor admin item.
What this means for sellers
Have the FIRM zone and certificate of insurance ready. Buyers in 2026 ask earlier than they did pre-reform.
Quote package to send insurers (copy/paste)
When you request quotes for a gulf-adjacent tower vs an inland golf home, send both carriers the same fact pack:
- Full street address and unit number
- Year built / substantial improvement year if known
- FEMA panel ID and zone from MSC printout (2024 FIRM context per City of Naples)
- Elevation certificate if the association or seller has one
- Master policy declarations page (towers) or prior HO-3 declarations (homes)
- Update frequency of shutters / impact glass
Identical inputs make the gulf vs inland premium delta apples-to-apples. Buyers who give the coastal tower fuller data than the inland home accidentally bias the comparison.
After the quote: association assessment math
A low HO-6 premium does not save you if the tower’s master wind deductible is large and the declaration allows assessments to recover it. Read assessment provisions beside the FEMA zone. Inland golf buyers should still pull NFHL—AE ponding panels appear away from the beach—and still quote flood when lenders or prudence require it.
Inland golf does not mean “no flood form”
Mediterra and Quail West buyers sometimes skip FEMA because the lifestyle feels inland. Pull the panel anyway. Lake, preserve, and drainage AE/AH designations appear in golf communities. The ask-order stays identical: FIRM → association/master policy → lender → personal quotes → lifestyle. Reversing the last two steps is how gulf-tower romance beats inland math before premiums are known.
City of Naples materials defining AE, AH, and VE exist specifically so owners stop relying on anecdotes. Use them. Pair with MSC printouts dated against the 2024 FIRM adoption context the City describes.
For towers, add a request for the association’s flood insurance decisions (building carries flood vs unit owners individually). That single email often explains a wide premium gap between otherwise similar buildings.
Lender vs cash buyers—same ask-order
Cash buyers sometimes skip flood insurance when a lender would have required it in AE/VE. The ask-order still starts with the FIRM. Knowing you are in Zone X vs AE changes whether flood is optional prudence or near-mandatory economics. Cash does not change storm physics.
For gulf-adjacent Naples towers, obtain:
- MSC zone printout
- Association master policy declarations (wind + flood decisions)
- Two HO-6 quotes using identical inputs
- One flood quote even if you hope to decline coverage
For inland golf, obtain the same MSC printout and an HO-3 package. Then compare total annual risk transfer cost beside HOA and club dues. That is the only fair gulf-tower vs inland-golf sheet.
One-afternoon field drill
Block three hours: (1) MSC printouts for two candidate addresses, (2) email both associations for master-policy declarations, (3) submit identical quote packets to one insurer. By evening you will know whether the gulf-adjacent tower’s lifestyle premium survives insurance math against the inland golf home. That single afternoon prevents a month of emotional touring on the wrong stack.
Why this ranks above finishes
Insurance and flood zone determine whether you can finance, what your escrow will be, and whether a special assessment after a storm is existential. Finishes do not. Keep the ask-order sacred even when a skyline view tempts you to skip FEMA. City of Naples 2024 FIRM guidance and FEMA MSC printouts are free; surprise premiums are not.
Document retention
Save MSC printouts, quote letters, and association insurance certificates in the same folder as your contract. Future refinance or resale buyers will ask for the same stack—and 2024 FIRM context will matter again when maps update.
FAQ
Is Zone X “no flood risk”?
No. It means outside the mapped high-risk SFHA. Storms still damage Zone X property. Quotes remain wise near the coast.
Do 2024 FIRMs change older condo docs?
Maps can change required insurance even when declarations are unchanged. Re-check the current panel.
Who pays a building’s flood deductible?
Often allocated via association documents after a storm. Read assessment provisions.
Should inland golf buyers skip FEMA?
Never. Drainage AE panels appear inland. One lookup prevents a bad assumption.
Sources
- City of Naples, Flood Zone Maps (accessed 2026-10-28)
- FEMA Flood Map Service Center portal (accessed 2026-10-28)
- Florida DBPR Condo resources (insurance / assessment climate context) (accessed 2026-10-28)
- Pelican Bay Foundation (association document hub example) (accessed 2026-10-28)
- NABOR market statistics (accessed 2026-10-28)
- Collier County Property Appraiser (parcel identification) (accessed 2026-10-28)
Your next step: Need a gulf-tower vs inland-golf insurance ask-order on real addresses? Reach Mike Pepple, Engel & Voelkers Naples, at 239-777-8870 or Mike@GulfAndGreens.com.
Last reviewed October 28, 2026.
Community rules, HOA and club terms, fees, and availability described here can change and should be verified directly with the community, association, or club before you make a decision.
Written by